

Borrow Money Instantly - Fundi

- 2.13K Reviews
- 4.7
- Downloads
- 500,000+
Our take on Borrow Money Instantly - Fundi from Appgk
I approached Borrow Money Instantly - Fundi as a finance app for a very specific moment: when someone needs to explore a short-term cash advance without spending a long time moving between unfamiliar services. Its purpose is easy to understand, but borrowing money is never a decision I would make from a quick glance at a store summary. The useful question is whether the app feels clear enough to navigate when I am stressed, whether the information is readable, and whether the process gives me enough room to make a careful choice.
Fundi is free to install, aimed at everyone, and developed by Sunny Pal Singh Gill. It belongs to the finance category rather than budgeting, investing, or everyday banking, so I see it as a borrowing tool rather than a complete money-management solution. The app has reached over 500 thousand installs and holds a 4.7 average from around 38 thousand ratings, which suggests that many people have found it worth trying. That popularity is useful context, but it should not replace checking the actual borrowing terms shown for an individual application.
How Fundi feels to read and navigate
A direct starting point, with an important need for patience
The strongest part of the concept is its directness. The name and purpose tell me quickly why I would open it: I am looking for an instant loan or cash advance, not a general financial dashboard. That focus can help a person who is already under pressure because there are fewer unrelated tools competing for attention. The current release is version 1.0.6, and the app supports Android 5.0 or later, making it available to people using older Android devices as well as newer phones.
That broad device reach matters for inclusive use. Not everyone replaces a phone regularly, and people managing tight finances may be especially likely to keep an older handset. A finance app that still runs on an older Android version can be more practical than one that quietly excludes those users. At the same time, an older operating system may offer a less comfortable experience for text scaling, screen readers, contrast settings, or touch response, so I would judge the experience together with the phone rather than assuming the minimum requirement guarantees smooth access.
Best Parts of Borrow Money Instantly - Fundi
Things to Keep in Mind About Borrow Money Instantly - Fundi
When I use an app in a borrowing situation, I want the first screen to answer three questions before I go further: what am I applying for, what information will I need, and what will I be expected to repay? Fundi’s central idea is simple enough to get me moving, but that simplicity should not encourage rushing. A short path is helpful only when each step explains its consequences in plain language.
Reading financial information without guessing
Readability is more than large lettering. For a loan app, the important content includes amounts, repayment timing, possible charges, eligibility conditions, and the difference between an estimate and a confirmed offer. I would slow down whenever a screen uses compact labels, unfamiliar financial terms, or a prominent action button that makes the next step feel more urgent than the surrounding explanation.
News and Features Related to Borrow Money Instantly - Fundi

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
My practical advice is to read every amount from left to right and compare the requested amount with the total repayment rather than focusing only on the cash received. If the app presents several figures, I would take a screenshot for my own reference or write them down before continuing, provided that doing so does not expose private information. This is one of the most useful habits with Fundi because a fast approval process can make a person remember the attractive number and overlook the obligation attached to it.
I also would not treat the 4.7 average as evidence that every applicant will receive the same experience. Ratings describe other users’ overall reactions, while approval, terms, and suitability can differ from one person to another. The app is free to download, but that does not mean borrowing through it is free. I would separate the cost of accessing the app from the financial cost of accepting a loan.
Don't want to read the full review?
Navigation for people who need a calmer pace
Someone with dyslexia, reduced vision, attention difficulties, or limited confidence with financial language may need more time than the app’s instant-loan framing suggests. I find that the best approach is to treat each screen as a form to review, not a countdown. Read headings first, then supporting text, then the action button. If the wording is unclear, stop before submitting personal details.
For users who rely on Android’s larger text setting, the real test is whether labels remain complete and buttons stay usable when text grows. I would also check whether the phone’s display magnification makes the whole form awkward to move through. These are not minor details in a finance app: a clipped repayment term or a button that shifts position can lead to an avoidable mistake.
Screenshots
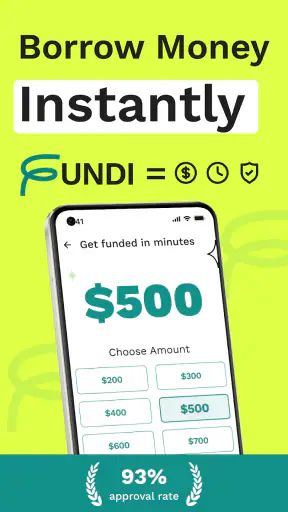
Motor and sensory considerations during an application
Loan applications can involve repeated tapping, typing, selecting options, and reviewing personal information. That creates a different challenge for someone with tremors, limited dexterity, joint pain, or fatigue. I would use the phone in a stable position, increase the system touch-and-hold timing if needed, and avoid completing the process while walking or multitasking. A mistake in an ordinary app is annoying; a mistake in a borrowing form can have financial consequences.
Voice input may help someone who finds typing difficult, but I would use it cautiously around sensitive information. Speaking financial or identity details in a shared room can create a privacy problem even if it makes the form easier to complete. An external keyboard can also assist users who struggle with a small touchscreen, although the exact behavior will depend on the Android device and the form itself.
For sensory access, I would pay attention to more than visual appearance. People with light sensitivity may prefer a darker system display or reduced brightness, while users with color-vision differences should not have to rely on color alone to understand an error or a selected option. I would look for accompanying text, symbols, or clear state changes. If a warning is communicated only through a subtle color difference, I would consider that a meaningful barrier to completing the process confidently.
Users with hearing loss are unlikely to need audio for the basic purpose of a borrowing app, but any alert or confirmation should ideally be understandable on screen as well. I would not assume that a sound means an application has been accepted. The only safe interpretation is the written status shown inside the app, together with the terms attached to it.
Situational access when money pressure is high
The most realistic use case is not a relaxed evening of financial planning. It is a person facing a same-day expense, perhaps an overdue bill or an urgent household purchase, opening Fundi on a phone with a low battery or a weak connection. In that situation, the app’s focused purpose can be valuable because the user does not need to search through a large banking suite. Yet pressure also reduces attention, so the fast route should be balanced with a deliberate pause before accepting anything.
I would prepare before opening the app. I would know the smallest amount that solves the immediate problem, check when my next reliable income arrives, and decide what repayment would leave enough money for food, transport, housing, and existing commitments. This workflow is more important than speed. Asking for the maximum visible amount simply because it is available can turn a temporary gap into a larger monthly problem.
Fundi may also be useful for someone who has limited access to traditional banking tools or who finds a full bank application overwhelming. Its finance focus and free entry point lower the initial barrier to exploring a cash advance. However, a person using a shared phone should be especially careful. I would avoid saving sensitive information in screenshots, clear copied data from the clipboard, lock the device, and sign out of any account when the session ends.
For users with limited data, an older phone, or inconsistent connectivity, a shorter app journey may be easier than a heavy financial platform, but interrupted forms can still be frustrating. I would avoid starting an application when the connection is unstable and would not repeatedly press a submission button if the screen appears frozen. Duplicate attempts or uncertainty about whether a request went through are exactly the kind of situational problems that call for patience.
Where the app may not be the right choice
Fundi is not my first recommendation for someone who needs a long-term debt plan, a detailed spending overview, or help comparing several forms of credit side by side. A credit union, bank, or nonprofit financial counselor may be better when the goal is a lower-cost structured solution rather than immediate access. A budgeting app may be more useful when the real issue is recurring cash-flow imbalance rather than one isolated emergency.
I would also skip an instant-loan application if I already know that repayment will depend on taking another loan. That pattern can become difficult to break, regardless of how clear the app is. Likewise, anyone who cannot comfortably read the terms, understand the total obligation, or protect their personal information should wait and seek help from a trusted person or qualified adviser.
Another trade-off is convenience versus comparison. A focused app can reduce friction, but it may also make one route feel like the obvious route. Before accepting an offer, I would compare it with my bank’s overdraft options, a local credit union, an employer advance if available, or a payment arrangement with the company I owe. The quickest application is not automatically the least expensive solution.
Small habits that make the experience safer and more inclusive
- Set a personal borrowing limit first: decide the amount needed before the app presents possible choices, so urgency does not determine the figure.
- Review the repayment total separately: do not stop at the amount deposited; identify what leaves your account and when.
- Use accessibility settings before starting: adjust text size, contrast, magnification, or touch timing on the phone, then check that the whole form remains usable.
- Create a private review moment: complete the application where other people cannot see your screen or hear sensitive information.
- Keep a written record: note the application status, repayment date, and agreed figures in a secure place rather than relying on memory during a stressful day.
These steps are especially helpful for people who process information slowly, use assistive settings, or are dealing with fatigue. They also improve accuracy for anyone. Inclusive design is not only about disability; it is about making a high-stakes task manageable when the user is distracted, anxious, short on time, or working with an older device.
What I would want to confirm before accepting
Before moving from exploration to commitment, I would look carefully for the exact repayment schedule, the complete cost, eligibility requirements, and the consequences of missing a payment. I would also check how the app identifies the status of an application and where the final agreement can be reviewed later. These questions are more important than whether the opening screen looks polished.
I would not assume that “fast approval” means guaranteed approval, nor would I interpret an initial form as a final offer. The store summary presents Fundi as a way to seek an instant loan and cash advance, but the responsible decision happens only after I understand the terms shown for my own situation. If a screen uses vague wording, I would pause rather than fill in the gap with an optimistic assumption.
People who need support from another person should decide in advance how to share the information safely. Reading the terms aloud with a trusted family member may help someone with low vision or limited financial literacy, but personal identification details should not be casually forwarded through messages or left visible. Assistance should make the decision clearer without handing control of the account to someone else.
My inclusive verdict on Fundi
I see Fundi as a focused entry point for people who want to investigate a short-term borrowing option on Android, especially those using older devices or who prefer a dedicated finance tool instead of a broad banking app. Its free access, clear purpose, and wide availability make it approachable. The developer is Sunny Pal Singh Gill, and the app’s current version is 1.0.6, with an Everyone age rating that keeps the presentation open to a broad audience.
Its accessibility value is best understood as practical rather than guaranteed. The Android requirement can help people with older phones, and the narrow purpose may reduce navigation overload, but inclusive use still depends on readable screens, usable text scaling, clear error messages, and the user’s ability to review sensitive financial information. I would test those points on my own device before relying on the app for an urgent application.
My recommendation is conditional: use it as a way to explore a cash advance, not as permission to borrow impulsively. If the terms are easy to read, the repayment fits comfortably into the budget, and the process works with your accessibility needs, Fundi may be a convenient option. If the cost is unclear, the repayment would stretch your essentials, or another provider offers a safer arrangement, choose the alternative. The most important feature here is not speed; it is being able to understand the commitment before saying yes.
After trying to view it through the needs of different users and situations, I would recommend Fundi to a careful borrower who values a direct route and is prepared to check every figure. I would not recommend it to someone seeking ongoing financial guidance or a solution to repeated debt. Used with a written plan, a private setting, and a deliberate review of the final terms, it can serve its narrow purpose. Without those safeguards, the convenience that makes it attractive can also make a costly decision feel too easy.
Borrow Money Instantly - Fundi FAQ
What is Borrow Money Instantly - Fundi, and how does it work?
Borrow Money Instantly - Fundi is a financial app designed to help eligible users request short-term loans or access funding through a mobile device. After creating an account, you may be asked to provide personal, identification, employment, and financial information. Fundi then evaluates the application and displays available terms, if approved. Approval, loan amounts, interest, fees, and repayment schedules can vary by applicant and location.
Who can use Fundi, and what requirements should I expect?
Eligibility depends on the country or region where Fundi operates and may include age, residency, a valid phone number, an accepted identification document, and a verified bank or mobile-money account. The app may also review income and repayment information before making a decision. Meeting the basic requirements does not guarantee approval, because lending decisions are based on the provider’s assessment and applicable regulations.
How quickly can I receive money after applying through Fundi?
The app promotes a convenient application process, but the actual time required to receive funds can differ. Verification, credit assessment, banking hours, weekends, technical issues, and the selected payment method may all affect the transfer. Some approved applications may be processed quickly, while others can take longer. Always confirm the stated disbursement conditions before accepting an offer.
What fees, interest, and repayment details should I check before borrowing?
Before confirming any loan, carefully review the total amount repayable, interest rate, service or processing fees, late-payment charges, repayment date, and any automatic-debit authorization. The cost of borrowing may differ according to your profile, loan amount, and local rules. Do not rely only on promotional wording; read the complete offer and make sure the repayment schedule fits your budget.
Is Borrow Money Instantly - Fundi safe to use, and what privacy precautions are important?
As with any financial application, use Fundi only through a legitimate app-store listing or the provider’s official website, and verify the developer information before entering sensitive details. Review the privacy policy and requested permissions, especially access to contacts, messages, location, or device data. Never share passwords, PINs, or one-time verification codes, and contact official support if an unexpected payment or suspicious request appears.











